Every analyst note this morning says the same sentence: the midterms will slow the data center buildout. CoreWeave fell 7 percent overnight, SpaceX 6, Oracle and Nebius 4 each. Wedbush's Dan Ives called the Texas governor's race the "biggest worry" of the night for the AI trade. All true, in the narrow sense. Wrong in the one that matters.
What voters killed on Tuesday was not the data center. It was the data center on the rate base: the model where a hyperscaler files a two-gigawatt interconnection request, a utility rate-bases a combined-cycle plant to serve it, and a retiree in Columbus pays for the transmission upgrade. That model lost the Ohio Senate race by five points, lost the Texas governor's race by seven, and lost both seats on the Georgia Public Service Commission. It is not coming back, and the people who spent 2025 building business plans on it should stop waiting for it.
What did not lose is demand for compute. JLL still projects nearly 100 GW of new global data center capacity between 2026 and 2030. Hyperscaler capex guidance did not move. OpenAI's response to the election was a plan to rebrand data centers as "AI compute campuses," which tells you they are adjusting the pitch, not the plan. The load is coming. The only question the voters answered is who pays for the generation, and the answer is the people who want the compute.
That answer has a consequence the stock market has not priced. The only way to pay for your own power on a timeline that matters is to show up with generation you already own. Which makes firm, deliverable megawatts the scarcest asset in American energy, and the election just made them scarcer.
Quick takeaways
- 56 percent of voters called AI and data centers a crucial or major factor in their vote for Congress. $173 million went into data center ads, almost all of it negative. Elon Musk spent $446 million and lost the race he cared most about.
- The incoming governors of Texas, Georgia, Ohio and Wisconsin all campaigned on some form of data center moratorium, and every one carries the same escape clause: bring your own generation and pay your own way.
- The OEMs cannot fill that order. GE Vernova has 122 GW under contract and heavy frames sold out through 2028; Wood Mackenzie puts lead times at six years. A slot signed today is a 2031 turbine.
- Behind-the-meter generation is about 2 GW operating nationwide. The gap between what the states now demand and what the factories can ship is the whole opportunity.
- Washington matters least. The one federal variable that moves the needle is whether the lame-duck Senate passes permitting reform before December 18.
What voters actually said
This was the first election where the grid was on the ballot, and the numbers are not subtle. Exit polling found 56 percent of voters called AI and data centers a crucial or major factor in their vote for Congress. Campaigns and outside groups spent $173 million on data center ads, almost all of it negative. Democrats alone put more than $100 million behind spots tying Republican incumbents to Big Tech, and won in Ohio, Kansas, Iowa, South Carolina and Texas on the back of them.
The other side of the ledger is more instructive. Elon Musk was the cycle's largest donor at $446 million, $168 million of it effectively on Ken Paxton. Paxton lost. A pro-acceleration super PAC seeded with over $100 million mostly sat on its money because candidates found the donations toxic; polling cited by TIME found three quarters of likely voters would be less likely to back a candidate who took AI super PAC cash. Blue Rose Research found Americans would rather live next to a prison or a nuclear plant than a data center.
The scoreboard, as the networks projected it Wednesday morning, and what each line means for power:
- U.S. Senate. Democrats 54 to 44, with flips in Texas, Ohio, Kansas, Iowa, Maine, North Carolina and South Carolina. Energy committee gavels, FERC confirmations and subpoena power change hands in January.
- U.S. House. A Democratic majority of at least 250 seats by MS NOW's estimate. Appropriations and the fate of federal preemption of state siting law now run through Democratic chairs.
- Texas governor. Gina Hinojosa (D) over Greg Abbott (R), 53 to 46, the first Democrat in 35 years. She campaigned on an immediate data center moratorium.
- Georgia governor and PSC. Keisha Lance Bottoms (D) flips the governorship, and Democrats take the Public Service Commission for the first time in 30 years. That is the body that approves Georgia Power's rates and its gas build-out.
- Ohio governor. Amy Acton (D) over Vivek Ramaswamy (R), on a conditional moratorium: pay 100 percent of costs, bring your own power.
- Wisconsin. David Crowley (D) and a Democratic trifecta. A pause pending review, and projects must be 100 percent renewable and cover all grid costs.
- Florida governor. Byron Donalds (R) over David Jolly (D). The one large Southeastern state that stayed friendly.
- Michigan Proposal 2. Passed. Utility PACs and executives can no longer fund state campaigns, a national first.
The mechanism underneath the anger is one every utility executive already understands. Large loads get socialized across the rate base through transmission upgrades, capacity charges and reserve margins. Residential customers in PJM, ERCOT and Georgia Power territory watched their bills climb while the beneficiaries were companies with trillion-dollar market caps. The industry's answer, that data centers use less water than golf courses, convinced nobody, and Blue Rose's Ali Mortell put the reason plainly: trust is so low that reassurance from tech companies and politicians does not land.
Voters do not care whether a GPU sits in Abilene or Ashburn. They care that the August bill went up and someone told them it was because of a building they never asked for. So the policy that follows targets the money, not the technology: who pays for interconnection, who pays for new generation, and whether the tax abatements survive.
Texas, and the four-state moratorium
Start with the number that explains everything. ERCOT's large-load queue held roughly 474 GW of connection requests, about 90 percent of them data centers, against a state that peaks in the mid-80s. That queue was never going to be built. The real question was which 10 to 15 percent of it would be, and Tuesday rewrote the selection criteria.
Texas was already a harder place to build before the election. Abbott ordered ERCOT and the PUCT to pause new data center grid connections pending an audit in August, halted TCEQ permits in September, and put 250 to 300 projects under review. The pause was bipartisan before it was a Democratic victory. What changed is that the governor who imposed it as an election-year hedge was replaced by one who campaigned on making it permanent until the Legislature writes rules on energy use, water and cost recovery, and on ending the 2015 law that hands hyperscale sites 20-year tax breaks.
The panic overstates her hand. Hinojosa takes office in January, the Legislature convenes January 12, and Republicans still hold both chambers in Austin, though Democrats were leading in a dozen or more Republican-held House seats. A statutory moratorium has to get through Dan Patrick's Senate. What she controls without a vote is slower and quieter: the PUCT appointments, the audit, state incentive approvals and the agenda of the session. Wells Fargo puts 27 percent of all planned U.S. data center gigawatts in Texas. Those projects did not die Tuesday. They became unpredictable, which is the thing capital hates more than hostile.
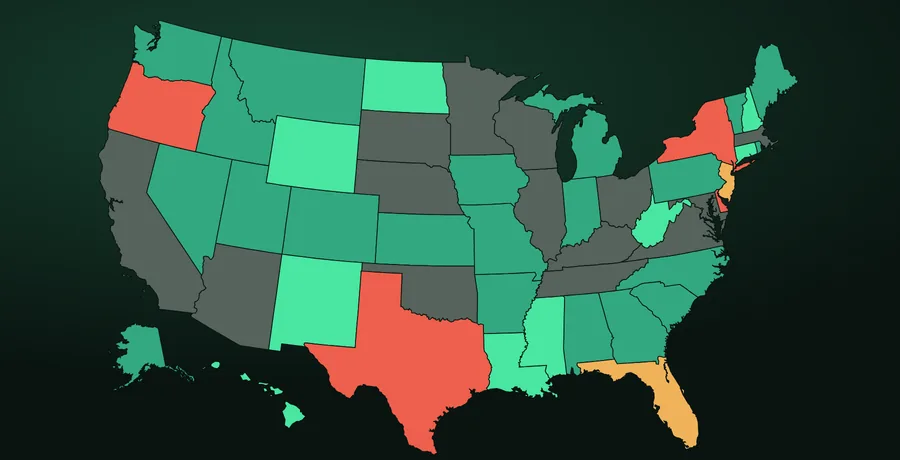
And Texas is not alone. Here is where the states that carry the load landed on Tuesday:
Positions from campaign platforms and victory statements as reported by Latitude Media, Grist and CNBC, 4 November 2026. "Flip" marks a governorship that changed party on November 3. Ohio's is a conditional moratorium; Wisconsin's a pause pending a statewide review.
What each one means for generation:
- Texas. The audit of 250 to 300 large-load projects continues, SB 6 large-load rules get a harder edge, and behind-the-meter becomes the only predictable path. The Legislature stays Republican, so a statutory moratorium is not assured.
- Georgia. Georgia Power's gas-heavy plan for data center load now faces a hostile commission, and the current rate freeze could be extended through 2031.
- Ohio. The bring-your-own-power condition is a direct order for on-site generation, on top of AEP Ohio's existing large-load tariff.
- Wisconsin. Project Lighthouse, the nearly 1 GW Oracle and OpenAI Stargate site, now sits in a state demanding renewable supply and full cost recovery.
- Michigan. $60 billion of planned utility capex through 2030 runs through a commission the utilities can no longer lobby with PAC money.
- Pennsylvania. PJM's largest state keeps a governor who has repeatedly threatened to pull it out of PJM over capacity prices, and House Democrats want storage, community solar and data center rules.
- Nevada. The large-load tariff debate reopens.
- Florida. Expect redirected hyperscaler interest; the governor favors gas and small modular nuclear for data centers.
Read the top band. The word "moratorium" now appears in the platforms of the incoming governors of Texas, Georgia, Ohio and Wisconsin. And every one of those moratoriums carries the same escape clause: bring your own generation and pay your own way. Ohio's Acton wrote it into her platform word for word. The policy is not "no data centers." The policy is "no data centers on the rate base."
Bring your own power, with what?
If the new state consensus is self-supply, the follow-up is where the supply comes from, and the honest answer is that it does not come from the OEMs on any timeline these governors will be in office to see.
GE Vernova reported on October 28 that its gas equipment backlog plus slot reservations reached 122 GW, up from 116 GW a quarter earlier, with heavy-duty deliveries sold out through 2028 and only about 10 GW left across 2029 and 2030. Siemens Energy's gas turbine backlog stands at 69 GW with another 26 GW under reservation. Wood Mackenzie now puts gas turbine lead times at six years and says the market has moved from fuel economics to procurement strategy as the thing that decides whether a project is viable. A slot reservation signed today is a 2031 turbine.
Against that backlog, the behind-the-meter market is still tiny. Roughly 2 GW is operating across four projects as of mid-2026, most of it xAI's Colossus site outside Memphis, and Cleanview expects 2.8 to 3.2 GW by year end. Developers are using, in Cleanview's phrase, anything they can get their hands on: aeroderivatives, reciprocating engines, mobile units on trailers. Nebius cannot get an air permit for a 400 MW onsite plant in New Jersey. The constraint did not disappear. It moved from the interconnection queue to the loading dock and the permit office.
Now layer Tuesday on top. Four large states just told developers to self-supply. Six-year OEM lead times mean a project sanctioned in 2027 under the new rules gets new iron in 2033, and nobody underwrites an AI campus on a 2033 power date. So the practical sources of firm generation for the next five years are three:
- Existing plants. Amazon's model of buying operating gas and nuclear assets and co-locating next to them. Expect more of it, and expect the new PSCs to fight the retail-load transfer every time.
- Secondary-market equipment. Turbines coming out of retiring or repowering plants, cancelled projects and overseas fleets. A used frame unit that can ship in months is worth more today than a new one with a 2031 slot, and the election widened that gap.
- Aeroderivative and reciprocating fleets. Smaller, faster, less efficient, and now the backbone of every early-phase campus.
The 474 GW queue will shrink. The projects that survive it will be the ones that showed up with their own turbines, and they will pay for the privilege. Policy uncertainty raises the premium on speed, and speed in this market is a function of what is already sitting in a yard, not what is on an order book.
Washington matters least, and permitting decides the premium
Start with what a Democratic Congress cannot do. It cannot override a veto. So it cannot restore the clean energy tax credits the One Big Beautiful Bill Act ended, cannot pass a national data center moratorium, and cannot enact sweeping AI regulation without the White House. Anyone writing today that the IRA is coming back is selling something.
What it can do, starting January 3, is oversight with teeth: subpoenas for DOE, FERC and EPA, hearings on canceled DOE awards and blocked renewable permits, hyperscaler executives in front of Energy and Commerce by spring. It can kill the Republican effort to preempt state AI and siting law, which means fifty state regimes instead of one, which means the table above matters more, not less. And it controls must-pass appropriations, so grid resilience and loan program funding are back on the table as the price of avoiding a shutdown.
The one thing that matters for generation is permitting reform, because it is the only policy both parties and the White House want. The Bipartisan American Affordability and Jobs Act, introduced September 30 by Capito, Whitehouse, Lee and Heinrich, is headed for a Senate floor vote in the lame duck ahead of the December 18 adjournment target. Wood Mackenzie calls it the single policy track with cross-party momentum. Democrats are split on whether to take the deal now or renegotiate from strength in January. John Podesta called the current bill a loaded Howitzer for fossil projects. Granholm and Steyer said take it. Jared Huffman wants to hold out.
For the power sector this is not a climate question. It is the difference between a 2029 transmission line and a 2034 one, and transmission is what turns a stranded plant into a dispatchable one. It is also the single variable that decides how big the behind-the-meter premium gets. If the lame duck produces a bill and FERC keeps the co-location door open, grid-connected projects get a second life and the premium on self-supply compresses. If Democrats wait for a better deal and Trump refuses to sign it, nothing moves for two years and every surviving project goes behind the meter. Watch the Senate floor in December. Then watch the first FERC nomination to run through a Democratic Energy and Natural Resources Committee, because that confirmation tells you whether co-location is a business model or a loophole.
Who wins and who loses?
The losers are real. Speculative developers holding queue positions and nothing else. Utilities that built their 2030 capex plans on data center load that will now self-supply, relocate or shrink. The OEMs, who just watched four states hand their customers a reason to buy used equipment rather than wait for a 2031 slot. And anyone who assumed Texas was a permanent free zone.
The winners are anyone who can put firm megawatts on a site in 2027 instead of 2031. That was already the trade before November 3. The election just made it the only trade.
The ratepayer backlash, pushed to its logical end, produces exactly the thing the grid needed: a class of large customers who bring their own iron. Self-supplied load is firm load. It does not file speculative requests across five ISOs, does not get socialized, and does not generate billboards reading "See that data center? Jon Husted did that." A hyperscaler that owns its turbines has a reason to run them, a reason to keep the local utility whole, and a reason to show up at the county commission with a check instead of an NDA.
The voters did not vote against the buildout. They voted to send it the bill. The buildout will pay it, in whatever deliverable generation costs, and the people holding that generation should know what they have.